Clarify the working range
Discuss income, debts, down-payment source and intended property type with a qualified mortgage professional. The real estate team does not turn a calculator result into an approval.
 COPPERFIELDHOMESReal Estate Partners · Real Broker
Coordinate pre-approval, deposit access, search strategy and the property-specific review without confusing an online estimate with a lending commitment.
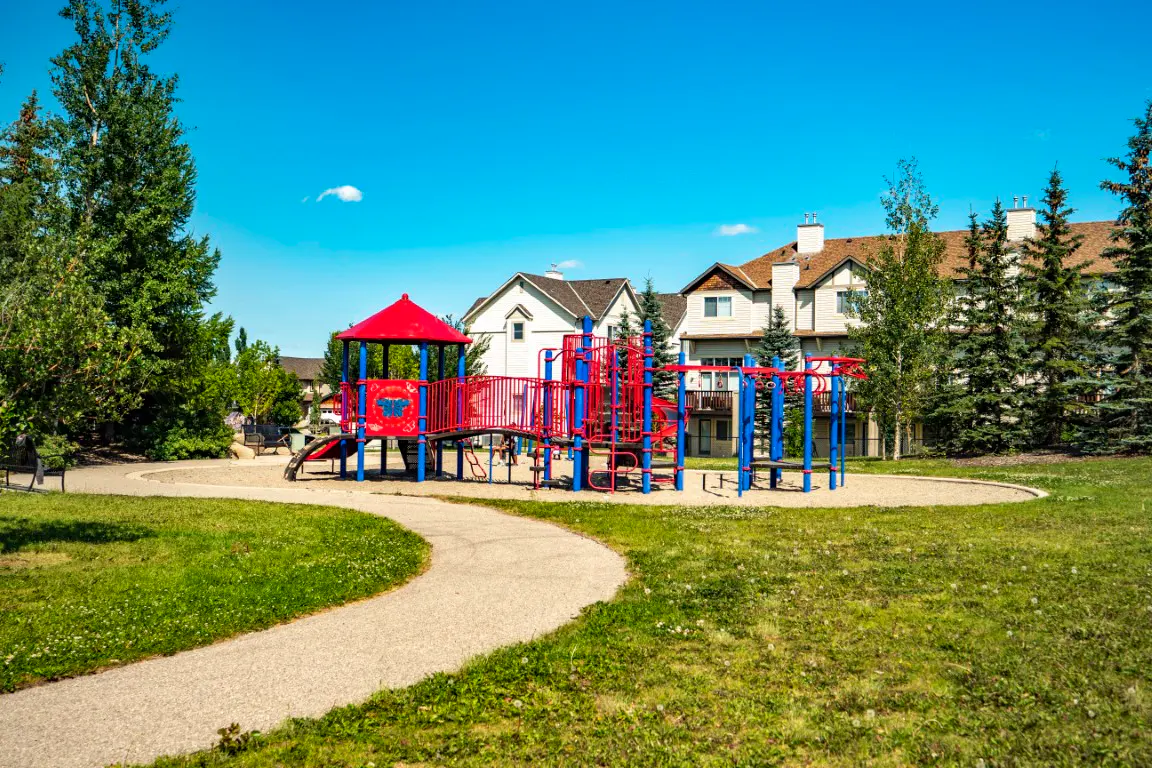
The right comparison separates effective age, condition, site and route exposure instead of treating every home in the community as interchangeable.
The useful outcome is not simply a maximum number. It is a documented plan that identifies the property forms, timing, cash requirements and professional confirmations needed before an offer deadline.
Discuss income, debts, down-payment source and intended property type with a qualified mortgage professional. The real estate team does not turn a calculator result into an approval.
Know the amount, location, transfer timing and documentation for the deposit before a competitive Copperfield opportunity compresses the schedule.
Leave room for inspection or document review, legal work, adjustments, moving, immediate repairs and the ownership costs tied to the actual property form.
Financing readiness does not replace review of current school designations, permit and renovation history, and route, site and insurance context. The offer structure still follows the property and available evidence. Confirm the current municipal land-use designation, permit history, approved plans and any nearby application for the exact Copperfield address.
Copperfield is an established community where property age, renovation history, lot position and immediate surroundings can produce meaningful differences between nearby sales. Begin the financing discussion with detached homes from varied build periods in view, then confirm how the actual property form, ownership obligations and near-term work affect cash and lender requirements. Row house: 675 occupied private dwellings (13%) in the 2021 Census profile.
Define the move, property forms, timing and a preliminary working range. For Copperfield, keep detached homes from varied build periods in the same decision as neighbourhood parks and local routes. Nearby alternatives in the same decision can include New Brighton and McKenzie Towne.
Prepare the income, asset, debt, down-payment and identity records requested by the chosen lender or broker. For Copperfield, keep attached choices where available in the same decision as everyday services and city connections. Nearby alternatives in the same decision can include McKenzie Towne and Mahogany.
Understand the approval conditions, rate-hold terms, property limitations and expiry date directly from the mortgage professional. For Copperfield, keep renovated and original-condition properties in the same decision as a range of commuting directions. Nearby alternatives in the same decision can include Mahogany and Auburn Bay.
Compare homes inside the approved plan while protecting room for property-specific ownership costs. For Copperfield, keep different lot, street and route contexts in the same decision as community amenities confirmed for the address. Nearby alternatives in the same decision can include Auburn Bay and New Brighton.
Before removing a financing condition, provide the actual property and current transaction documents to the appropriate professionals. For Copperfield, keep detached homes from varied build periods in the same decision as neighbourhood parks and local routes. Nearby alternatives in the same decision can include New Brighton and McKenzie Towne.
Use the dedicated pre-approval service for lending advice, and tell the real estate team what you plan to buy so the property search can be coordinated with it.
MortgagePreApproval.ca handles the mortgage-pre-approval path. The Real Estate Partners team remains available for the property search, community context and offer strategy.
Copperfield is an established community where property age, renovation history, lot position and immediate surroundings can produce meaningful differences between nearby sales. This record turns the community file into route-specific work while keeping the subject property and current professional advice separate.
Which Copperfield property form, ownership structure and completion stage fit the intended use and budget? For this financing-readiness plan, use that evidence to put the buyer's intended property and timing in the mortgage-professional conversation. Read it beside: Distinguish a feature inside the mapped community from one that is nearby, planned or accessible only from particular streets or phases. Comparison checkpoint: Auburn Bay. Compare Auburn Bay when buyers want another southeast lake-community option with distinct housing and amenity trade-offs. Current listing status still belongs to the approved live record.
3,400 occupied private dwellings were reported as single-detached houses in the 2021 Census profile (67%); 870 apartments in buildings with fewer than five storeys represented another 17%. Applied to the financing-readiness plan, the evidence helps ask whether this property form changes down payment, insurance, document or lender review. Read it beside: Describe nearby services as nearby rather than inside the community unless the mapped boundary and current source support that wording. Comparison checkpoint: New Brighton. Compare nearby New Brighton when the search includes southeast family housing, differing amenities and current alternatives at a similar total cost. Condition and legality still require the documents and review appropriate to the property.
Identify address-specific water, drainage, slope, noise, traffic, construction, fire, environmental or insurance questions relevant to the Copperfield property; do not generalize an exposure to every home. Within the financing-readiness plan, its job is to reserve cash and condition time for the address-level issue instead of assuming approval resolves it. Read it beside: Compare McKenzie Towne when buyers are weighing a broader mix of property forms, build eras and ownership structures. Comparison checkpoint: McKenzie Towne. Compare McKenzie Towne when buyers are weighing a broader mix of property forms, build eras and ownership structures. A lender or mortgage professional must decide how the actual property affects financing acceptance.
5,995 residents aged five and older had moved within the prior five years (46%); that is household-mobility context rather than a proxy for real estate turnover. The financing-readiness plan should use this record to test the real route and recurring ownership pattern before fixing the working housing budget. Read it beside: Caption improvements and inclusions precisely so buyers can separate documented value from decoration or staging. Comparison checkpoint: Mahogany. Compare Mahogany when lake-community amenities, newer housing and a different price and ownership mix enter the decision. Community context cannot establish value for the subject home.
The profile counted 14,095 people in private households across 5,050 households, with an average household size of 2.8 people. Here, the practical use is to keep the community baseline distinct from the lender's review of the actual collateral. Read it beside: Migration inventory, retained media and legacy page review. Publisher record: Real Estate Partners. Comparison checkpoint: Auburn Bay. Compare Auburn Bay when buyers want another southeast lake-community option with distinct housing and amenity trade-offs. A named source supports only the claim and geography recorded for it.
Compare nearby New Brighton when the search includes southeast family housing, differing amenities and current alternatives at a similar total cost. Carry this into the financing-readiness plan to compare the alternative area's property forms and total ownership obligations inside the same plan. Read it beside: McKenzie Towne — Compare McKenzie Towne when buyers are weighing a broader mix of property forms, build eras and ownership structures. Comparison checkpoint: New Brighton. Compare nearby New Brighton when the search includes southeast family housing, differing amenities and current alternatives at a similar total cost. A comparison relationship does not make two properties or communities equivalent.
Lead with the real differentiators of the Copperfield property: site, effective age, documented improvements, layout, ownership structure and immediate setting. For the financing-readiness plan workflow, use it to anticipate which condition or document a future seller file may need to explain. Read it beside: Match the inspection and document plan to the subject property's actual construction, additions and effective age rather than the community's largest Census-era cohort. Comparison checkpoint: McKenzie Towne. Compare McKenzie Towne when buyers are weighing a broader mix of property forms, build eras and ownership structures. Historical evidence must not be presented as current inventory or operating status.
Census population, household, tenure, dwelling-form and construction-period context. Publisher record: The City of Calgary. The next step in the financing-readiness plan is to record the evidence source before a local assumption enters the financing scenario. Read it beside: Identify address-specific water, drainage, slope, noise, traffic, construction, fire, environmental or insurance questions relevant to the Copperfield property; do not generalize an exposure to every home. Comparison checkpoint: Mahogany. Compare Mahogany when lake-community amenities, newer housing and a different price and ownership mix enter the decision. The paired records define the next question; they do not settle the property conclusion.
Compare the community, the type of home and the property-specific details in the order that makes sense for your move.
Keep financing readiness connected to the Copperfield search and property review.
Explore →02Account for the ownership costs and property limitations most relevant to this community archetype.
Explore →03Compare live choices within the working range while preserving room for closing and immediate ownership costs.
Explore →Start with the practical questions, then open the detailed guide that matches the property or decision in front of you.
No. A calculator is an orientation tool. A qualified mortgage professional must confirm income, debts, down payment, property limitations, conditions, rate terms and expiry.
3,400 occupied private dwellings were reported as single-detached houses in the 2021 Census profile (67%); 870 apartments in buildings with fewer than five storeys represented another 17%. Financing readiness should reflect the likely property form, ownership costs and any lender limitations.
Plan for legal work, inspection or document review, adjustments, moving, immediate repairs and the ownership obligations attached to the actual property.
No. Identify address-specific water, drainage, slope, noise, traffic, construction, fire, environmental or insurance questions relevant to the Copperfield property; do not generalize an exposure to every home.
Provincial guidance on purchase contracts, land titles, property reports and home inspections
Open official source ↗02Property ResearchThe City of Calgary · accessed 2026-08-26Address-level permits, land use and planning records
Open official source ↗03Municipal property assessmentGovernment of Alberta · accessed 2026-09-12Provincial context for municipal property assessment and its distinction from a property-specific market opinion
Open official source ↗Official records provide dated community context. Current listing status and conclusions about one property still require the applicable live record and property documents.
Dusko Sremac is the primary contact, backed by Real Estate Partners by Real Broker.